Rideshare and delivery gigs can help you make some extra money, but you’ll want to make sure you’re fully protected during your gig work. A regular auto insurance policy doesn’t cover any type of commercial activity, which means that you could find yourself facing large bills if you’re in any type of accident.
Riders vs. Commercial Insurance
If you primarily use your vehicle for personal purposes, you may be able to add a rider to your personal auto insurance policy instead of buying commercial insurance. A rider (aka endorsement) adds coverage for occasional commercial use, providing you with the protection you need to use your vehicle for both commercial and personal purposes. However, riders don’t offer as much liability coverage as a commercial auto insurance policy. What’s more, your insurer may deny compensation for repeated claims related to commercial activity.
If you do rideshare and/or delivery work on a very regular basis, commercial auto insurance is a worthwhile investment. It offers higher liability and property damage limits than personal auto insurance coverage. Furthermore, you won’t be denied compensation simply because the claim is related to commercial work.
Call Noyes Hall & Allen Insurance in South Portland, ME, for More Information
Our team at Noyes Hall & Allen Insurance is always happy to help South Portland, ME, drivers get the insurance coverage they need at a price they can afford. We offer various forms of auto insurance from multiple carriers to make it easy for you to find the policy that meets your exact needs. Give us a call, let us know what type of protection you need for your vehicle, and we’ll help you review your options to make informed coverage decisions.
Home insurance provides coverage for a range of problems. If your home has been recently damaged by a burst pipe, it’s important to know whether your home insurance will cover the cost of repairs. Your insurance agent at Noyes Hall & Allen Insurance servicing Portland, ME can help answer your questions. We can look up your insurance information, go over your coverage with you, and if you need to start a claim for water damage, we can help with that too.
Does Home Insurance Cover a Burst Pipe?
Typically, home insurance does cover a burst pipe. Most of the time, home insurance will only cover a burst pipe that was a sudden, unexpected occurrence. If the pipe was leaking and caused damage over a long time, your insurance is unlikely to cover this problem. Keep in mind that you are expected to maintain your home. If your pipes burst because you turned off your heat and the pipes froze as a result, your home insurance policy may not cover the damage.
Will Home Insurance Cover Damage from a Burst Pipe?
Usually, home insurance policies will cover damage to floors, walls, and ceilings when the damage comes from a burst pipe. To find out exactly what’s covered by your home insurance policy, contact your insurance agent.
How Can I Find Out More About My Coverage and Limits?
The professionals at Noyes Hall & Allen Insurance servicing Portland, ME are happy to answer your questions about your burst pipe. We can help you determine whether your coverage extends to your situation, and if you need to file a claim, we can help with that too. If you run into trouble with your insurance company, we can advocate for you to help you get what you need. Call today.
Business interruption insurance prevents a business from going bankrupt after incurring a catastrophic situation. This type of insurance allows a business owner to preserve their business plan and handle each responsibility they are faced with.
Lost Revenue
Business interruption insurance replaces the revenue that would be earned under normal circumstances. The insurance benefit that you receive will allow you to keep your business afloat during tough times.
It will ensure that you have the funding needed to handle all the expenses you typically face day-to-day. The manner in which lost revenue is projected may be reliant upon past sales and business records that you have at your disposal.
Recurring Bills
After a catastrophe, you will still be hit with recurring bills. This fact can be overbearing when faced with a crisis. Fortunately, business interruption insurance handles expenses like these.
An insurance benefit can handle utility costs, vendor costs, equipment costs, and more. If you are typically saddled with a wide range of expenses each month, it can be greatly beneficial to put your mind at ease by knowing that your business interruption insurance coverage will handle whatever expenses come your way.
Temporary Commercial Facility Fees
If flooding, a fire, or destructive vandalism has affected your place of business, you may decide to operate your business from another location. Moving your establishment to another address may be temporary. During this time, your business interruption insurance can assist with paying the bills associated with the move.
Agent Support in The Portland, ME Region
Are you ready to ask an agent questions about your insurance policy? If so, contact one of our representatives from Noyes Hall & Allen Insurance. An agent will go over your insurance coverage with you.
Home insurance and home warranty policies provide important forms of coverage for your home. Even so, there are important differences between the two.
Home Insurance
Home insurance covers your home structure, other structures on the property, your appliances, and your personal belongings in the home. If these are damaged or destroyed by a covered peril, you’ll be compensated. If you have to move out of your home temporarily while the home is being repaired after a covered peril, home insurance will cover the cost of food and accommodations.
Home insurance also covers liability and property damage that occurs on your premises. If someone has an accident in your home, insurance can cover medical bills and other expenses. The same point applies if someone’s personal property is damaged while they’re visiting your home.
Furthermore, home insurance can be customized to meet your specific needs. You can add a rider to your policy to cover short-term rentals. You can buy umbrella coverage to increase your home insurance liability policy limits.
Home Warranty Policies
A home warranty only covers appliances in the home. However, unlike home insurance, a home warranty policy covers damage caused by regular wear and tear. If something breaks down, you pay only a pre-determined fee, and the item is either repaired or replaced. A home warranty policy is especially valuable if your home has older appliances that are no longer covered by a manufacturer’s warranty.
Call Noyes Hall & Allen Insurance in South Portland, ME, for More Information
Noyes Hall & Allen Insurance is a local insurance agency serving homeowners in and around Portland, ME. We take pride in helping our customers find the best home insurance deals at the best possible price. Call us today to find out more about our policies and policy bundles.
Taking care of your car can be expensive. From routine maintenance to the investment in new tires, you may spend a significant amount of money every year on your vehicle. It is logical to wonder if insurance can help with those costs. There are limited situations where your policy can cover new tires.
At Noyes Hall & Allen Insurance, we can help you determine what coverage is a part of your plan. If you need auto insurance in Portland, ME, give us a call to inquire about your options.
When Does Auto Insurance Cover Tires
It is not common for your auto insurance policy to cover the cost of replacing your tires for normal wear and tear. Rather, auto insurance is there to help you in unexpected and accidental situations to minimize the costs. For example, if you are in a car accident, and the tires suffer damage to them because of the collision, and that collision is covered, the insurance company will pay for new tires.
Some types of policies, like collision insurance, may offer limited protections if you strike surfaces that cause damage to the tires, such as significant potholes that bend your rim. You may also turn to your policy for help with vandalism and theft of your tires, assuming you purchased comprehensive insurance coverage.
There are situations where you can purchase tire insurance or roadside assistance. Less common and only available as an add-on to your policy, these can help you to get new tires in place when a covered event occurs.
Get Coverage You Can Count On
Set up some time to speak to our team at Noyes Hall & Allen Insurance now. Learn about the types of coverage we can offer to you. When you need quality auto insurance in Portland, ME, we can help.
If your home insurance renewal arrived this year with a number that made you do a double-take, you’re not imagining things — and you’re not alone.
Home insurance premiums across Maine have increased significantly over the past several years. Before you assume there’s nothing you can do, it helps to understand why it’s happening and what your options actually are — especially if you’re working with an independent insurance agent in Maine who can shop the market on your behalf.
Why Is Maine Home Insurance Getting More Expensive?
The short answer: insurance is priced on risk, and the cost of risk has risen sharply nationwide — even in places that haven’t had major local losses.
Rising Reinsurance Costs
Insurance companies buy insurance too — it’s called reinsurance, and it protects them from catastrophic loss years. After a stretch of expensive hurricane seasons, wildfires, and severe storms across the country, reinsurance prices spiked. Maine insurers pay those higher costs, and some of that flows to your renewal.
Higher Construction and Repair Costs
Replacing a damaged home costs a lot more today than it did five years ago. Labor and materials — especially lumber — saw sharp inflation post-pandemic. Your homeowners insurance in Maine needs to reflect what it would actually cost to rebuild your home today, not what it cost when your policy was first written. Many carriers have adjusted replacement cost estimates upward, which increases the premium.
Carrier Underwriting Changes
Some insurance companies have pulled back from certain markets or tightened their eligibility requirements. When carriers reduce their appetite, competition shrinks — and prices reflect that. This is especially relevant in Maine, where fewer carriers compete for certain types of homes and locations.
What Can Mainers Do About Rising Home Insurance Costs?
None of the factors above are your fault. But you shouldn’t simply accept a renewal you haven’t had anyone review. Here’s what’s worth knowing.
Work With an Independent Agent Who Shops for You
If you buy home insurance directly from a single company — online or through a captive agent — your only real option when the price goes up is to accept it, reduce your coverage, or start over somewhere else on your own.
When you work with an independent insurance agency like Noyes Hall & Allen in South Portland, Maine, you have someone who represents multiple carriers. That matters at renewal time.
We review our clients’ renewals and actively shop their coverage when rates move in ways that don’t make sense. If your current carrier has raised your Maine homeowners insurance premium and another company we represent can offer comparable coverage at a better price, we’ll find it. If your current carrier is still your best option, we’ll tell you that honestly — and explain why.
Make Sure Your Coverage Still Makes Sense
A renewal is also a good time to review what you actually have. Some homeowners are paying for coverage limits or options that no longer fit their situation. Others are underinsured and don’t realize it. A review with your agent can identify both.
Be Careful About Cutting Coverage to Save Money
It can be tempting to raise your deductible or drop optional coverages to offset a premium increase. Sometimes that’s the right call — but not always. Before you make changes, talk to an agent who can walk you through the tradeoffs. Saving $100 a year on your premium isn’t a good deal if it leaves you with a $5,000 gap after a claim.
Why Greater Portland Homeowners Work With Noyes Hall & Allen
Noyes Hall & Allen has been helping Maine homeowners navigate the insurance market since 1928. We’re an independent agency in South Portland, which means we’re not locked into one carrier’s products or pricing. We represent close to 20 insurance companies and our job is to find the right fit for you — not to push one company’s product.
When your renewal arrives, you shouldn’t have to figure out on your own whether it’s fair. That’s what we’re here for.
Get a Second Opinion on Your Maine Home Insurance Renewal
If your homeowners insurance renewal is coming up — or if you’ve already renewed and are still frustrated by the price — reach out to us. Bring your current declarations page if you have it. We’ll take a look at what you have, what you’re paying, and whether there’s a better option available in the Maine market.
The secret is out: Portland, Maine is a great place to live. Friendly neighbors, excellent restaurants, and safety make it a popular choice for families and retirees.
Even in a safe place like Maine, bad things can happen. If you have to file a home insurance claim you want to be confident that your insurance policy will help get life back to normal. When it comes to home insurance, you want to know that your agent is on your side. The team at Noyes Hall & Allen Insurance has been committed to you since 1933.
How Does a Home Inventory Help Me?
When you file a home insurance claim, your insurance company needs to know what you lost. Then they pay you to replace it. Imagine after a tragedy trying to remember everything you had in your home, every drawer and cabinet. It’s overwhelming.
You can avoid stress and frustration by preparing a home inventory. This creates a record of all the rooms in your home and what was in them. You can do it with a video walkthrough of your home, computer spreadsheet or even on paper. Either way, aim for as much backup information as possible, and update periodically. Recording details like model numbers and receipts are a good start. Store the inventory in a safe place, and back it up in the cloud or in your safe deposit box.
We are independent agents. That means we offer you lots of choices from a wide variety of insurance companies. We will help you find the best value for the coverage you need. We’re independent and committed to you.
Conditional renewal occurs when your insurance company makes changes to your policy that you did not request. These changes can range from minor adjustments to significant alterations. It’s essential to understand what these changes mean for you..
When Do Insurers Use Conditional Renewal?
Insurance companies often change underwriting requirements. They often “grandfather” in-force policies from these changes. But sometimes conditions change dramatically. Then the insurance company decides to make wholesale changes, even to in-force policies. Or, the insurance company may take a specific action on your policy.
Common Conditional Renewal Types
These are the most common changes in a conditional renewal:
Deductible changes – This could mean an increased deductible or the introduction of a new type, such as a separate wind or hurricane deductible.
Liability Limits – Your liability insurance protection might be reduced, for example, from $500,000 to $100,000.
Coverage exclusions or reductions – Certain coverages, like towing or roadside assistance, might be removed or reduced.
Large rate increases – Some states require notification of significant price increases, though this is not the case in Maine.
Why Am I Getting a Conditional Renewal?
Your insurer might be implementing an across-the-board change, such as a new minimum deductible or a wind deductible for any property in a certain location.
Or the underwriter could be taking specific action on your policy. This is usually in response to claims or some condition that they’ve identified. In this kind of conditional renewal the notice will list the reasons.
Is the Insurance Company Canceling My Policy?
No, a conditional renewal is NOT a non-renewal. The insurance company is offering to renew your policy, however with different terms than before. On the other hand, if the insurance company mails you a Notice of Nonrenewal, they are terminating your contract.
Do I Have Options?
You’re not required to accept the conditional renewal, but it might still be the best deal for you. Conditional renewal is often a re-calibration to the market. In other words, your insurance company is doing what most new insurers would do.
However, you can check with your Noyes Hall & Allen agent to see what they think. We offer a choice of several insurance companies. That gives us good perspective on the market so that we can provide personal advice for your specific situation. We like to say we’re independent and committed to you.
Despite Maine’s cool, wet June weather, pool season is here once again. Swimming pool insurance is important to protect your family, friends and financial assets.
Sobering Water Safety Statistics
Drowning is second only to auto accidents as the most common cause of unintentional injury-related death for children under 14, according to the American Red Cross. According to an ARC survey, 48% of respondents said they had nearly drowned at some point in their life.
Pool injuries aren’t limited to the water, either. Slippery deck surfaces and other equipment can cause trouble too. The Red Cross’ web site has excellent water safety advice.
Five Smart Pool Insurance Tips
Make Sure Your Pool is Up to Code
Plumbing, fencing and deck requirements can vary by locality. If your pool doesn’t meet current codes, your risk increases greatly.
Supervise Pool Activity
And it only takes seconds for tragedy to happen. Make sure a strong-swimming adult is present when the pool is in use. Use an alarm to prevent accidental, unsupervised or unwanted use of your pool.
Pool Insurance Requires a Fence and Lock
This is required in most locales for in-ground pools and for many above-ground pools.
Carry Adequate Pool Insurance
If someone is hurt while using your pool, insurance may be the only thing between you and bankruptcy. Make sure your liability limits are high enough to protect your net worth and earnings potential. A great idea: buy an umbrella policy, which provides even higher limits than homeowners coverage.
Consult Your Insurance Agent
Many insurers do not charge an extra premium for swimming pools, but they usually have underwriting requirements. These are designed to manage the company’s – and your – risk. For example, many companies will not insure pools with slides or diving boards, or without locking fences.
Don’t let tragedy spoil your summer fun when warmer weather finally comes to Maine. If you live in southern Maine and have a swimming pool, contact Noyes Hall & Allen Insurance for a review. We offer a choice of Maine’s top insurance companies. We’re independent and committed to you.
Maine home and auto insurance rates are rising faster than the national average in 2024. Although Maine rates are still among the lowest in the USA, Portland Maine area insurance buyers saw almost a 15% price increase in the first half of 2024. Industry experts expect this to continue through 2024, with some optimism that the increases will be less next year.
Maine Auto Insurance Rates – June 2024
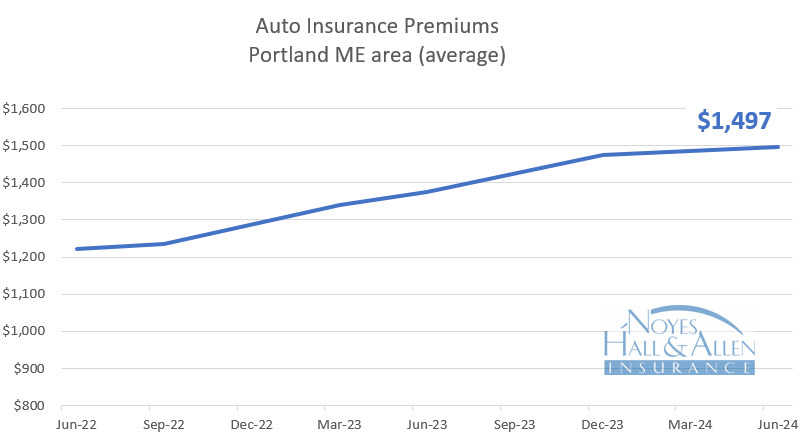
Portland Maine auto insurance rates jumped 13.0% on average in the 2nd quarter of 2024. The average annual auto insurance policy in Cumberland County now costs $1497 per year. Rates vary depending on the type and number of vehicles, drivers and other factors.
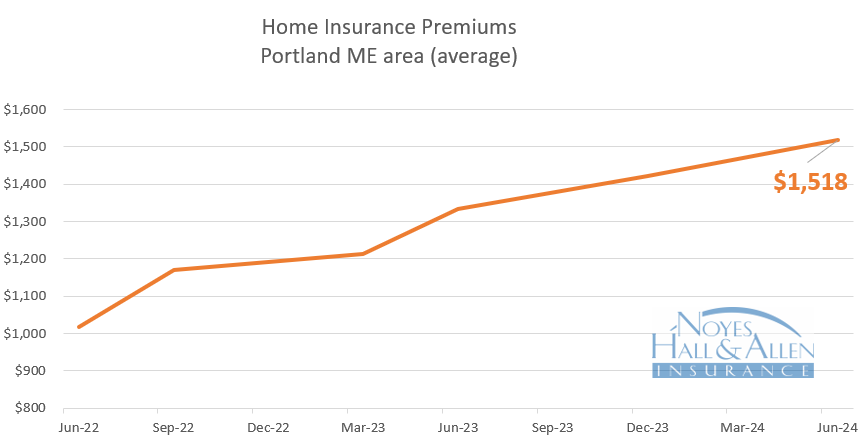
Maine home insurance rates continue to increase even faster than auto insurance. The average home insurance premium was 13.7% higher than a year ago. The end is not in sight yet, as US home insurers report record losses from weather events.
Fortunately, historically high rebuilding costs have tempered somewhat. This allowed insurance companies to reduce their “inflation guard” factors. That reduces the percentage increase, which was about 4 percentage points lower than our last survey in December.
Independent Agents Offer a Choice of Maine Home and Auto Insurance Rates
For more than 90 years, Noyes Hall & Allen has helped southern Mainers navigate the insurance market. While we don’t have any control over prices, we offer a choice of several insurance companies. That means we can help you find the best insurance value in any market.